


For pretty much every way there is to tax and regulate you and me? There are ways for Big Business and their oligarchs to minimize said taxes and regulations. When they’re not getting out of them altogether.
Sometimes it’s as easy as this: The elected puppets — oops, I mean officials — we pretend represent us, ignoring the laws they imposed upon us when it comes to Big Biz.
A prominent current example is the state and local elected puppets granting often massive, often decades-long exemptions to property tax laws and construction regulations for Big Tech and their massive data centers.
Property taxes for homeowners are reaching a critical mass all across the U.S. Isn’t it additional fun to force them to cover the property taxes of the richest companies in human history?
Sometimes it’s as easy as: The elected puppets ensconce their Big Biz cronyism in law. By having their Big Biz cronies write the law.
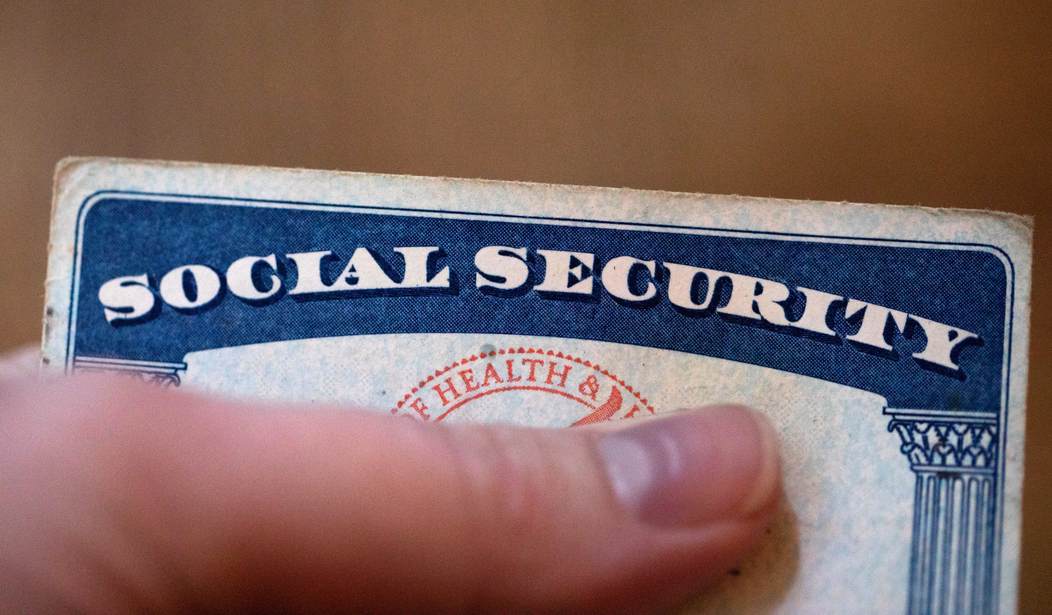
Perhaps the quintessential example of this is how the federal government levies taxes. Let us look at this through the prism of Social Security and its taxes.
Lest we forget: Social Security is about $69 trillion short over the next 75 years, which is almost $1 trillion per year. And it totally runs out of money in 2032. (The year I turn 62 and first become eligible. Thanks, Ladies and Gentlemen of D.C.)
Social Security and its taxes:
It’s a flat payroll tax. Employers withhold 6.2% from each paycheck and match it with another 6.2% on their end, so the full 12.4% comes out of wages up to a wage base that adjusts yearly for inflation.
For 2026 that cap sits around $184,000. Self-employed people pay the whole 12.4% themselves through self-employment tax, though they get to deduct half of it. Anything above the cap isn’t taxed for Social Security…
Say a regular guy averaged a $50,000 annual income for 40 years. Say ages 17-67. That totals out to $2.0 million. 12.4% of that is $248,000.
If he retires in 2026 at age 67 — the current full-benefit age — he’d receive about $2,400 a month in Social Security. Oh, and the average cost of living in the U.S.? Is about $3,300 per month.
It will take him over eight and a half years just to break even on what he was taxed. So to almost 76 years old. Oh, and the average U.S. lifespan is 79 years old.
Of course, this reminds us of the ZERO growth on his money Social Security delivers. If his money had earned just 2% interest compounded over those 40 years? His $248,000 would have become $374,000. An extra $126,000. An extra 33-plus%.
Or almost $3,200 a month. Which is a lot closer to that national average cost of living.
But here’s the really fun part: As mentioned above, zero taxes are collected above the salary threshold of $184,000. You can earn a per annum salary of $20 million? And only the first $184,000 is taxed.
But your Social Security retirement payment is based upon your highest thirty-five years of inflation-adjusted earnings—capped via a progressive formula.
The net result: You get paid by Social Security on the $20 million per annum — a whole lot more than you were taxed on it. The $20-million-dollar-man gets the current maximum monthly benefit of $5,181. Or more than double what our regular guy receives.
It gets really fun when the really rich pay ZERO dollars in Social Security taxes. There are more ways than income for the really rich to get paid — or pay themselves.
There are carried interest earnings. This is how hedge fund pirates pay themselves for destroying the U.S. economy. Carried interest earnings are taxed at the long-term capital gains rate — around 20%. (Though it can be set up to be as low as 10%.) None of which goes to Social Security.
Speaking of capital gains: That income — in all forms, at all rates — is exempt from Social Security taxes.
Of course: If you spend your entire working life earning only carried interest and/or cap gains? You don’t qualify for Social Security payments on the back end. Pity the poor hedge fund pirates and the idle rich.
But Jeff Bezos and Elon Musk are going to be legally eligible for Social Security. Bill Gates and Warren Buffett are legally eligible right now. (And what do you want to bet that all four cash those checks?)
But then there’s the most fun. The nigh-total tax avoidance scam: The intergenerational, multiple lifetime loan.
To fund their lifestyles, the wealthy borrow against their stocks and other assets, pretty much all of which appreciate at a much higher rate than the uber-low interest rates they get on their loans. It’s basically free money.
And because they’re rich? They can renegotiate the loans again and again. And only ever pay the interest — throughout the entirety of their lives.
And when they die? Then comes some serious government cronyism. It’s called Stepped‑Up Basis: A step-up in basis sets the cost basis of inherited property to its fair market value on the date of the previous owner’s death. If an heir sells inherited property, the step-up in basis they received can greatly reduce their capital gains tax liability.
Get that? When our billionaire dies? All the values of all his assets? Reset their cap gains taxable value to the day he died.
So, for example, what began as a $20 million portfolio at age 20 became a $20 billion portfolio at the time of death. But any posthumous sales of any of the assets? Pays ZERO tax on that 99,000% gain in value.
Yes, the heirs inherit the billionaire's lifelong lifestyle loan debt. Which they can instantaneously pay off by selling an infinitesimal fraction of the inherited assets — at a near-0% cap gains rate. And then the heirs start the lifestyle loan merry-go-round all over again.
The federal government taxes basically none of that money. So of course Social Security gets none of it.
I think we’ve so bastardized the original idea behind Social Security? We can now freely alter how we tax for and fund it. Especially considering it’s going WAY broke — WAY fast.
Let’s eliminate the cap on Social Security-taxable income. You make a $20 million salary? You pay Social Security taxes on all $20 million. $40 million? $40 million. Etc.
Let’s Social Security tax all capital gains — including carried interest.
And let’s please — for the love of all that is sane — cap the Stepped-Up Basis at a much-lower-than-billionaire amount. To protect farmers — not family fortunes.
And let’s do all of that — before we even consider the drastic 22% cut set to be automatically imposed in 2032 when the program runs out of cash.
It would be nice to have a tiny modicum of sanity injected into the nation’s tax and program codes.
Editor's Note: Do you enjoy PJ Media's conservative reporting exposing the radical left and woke media? Support our work so we can keep bringing you the truth.
Join PJ Media VIP and use promo code FIGHT to receive 60% off your membership.
Join the Conversation
VIP members get the ability to comment on articles.