


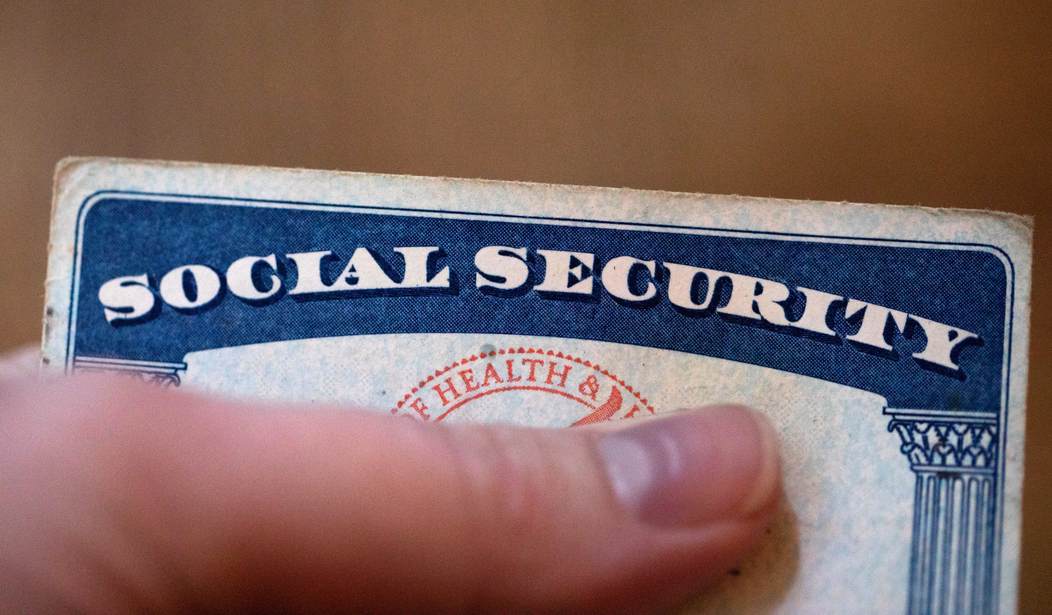
If you take a look at your last pay stub, you will find a line marked OASDI. It stands for Old-Age, Survivors, and Disability Insurance, which is the formal name for Social Security. The tax on that line is 6.2% of your wages. What you do not see on that stub is that your employer paid a matching 6.2% of your paycheck directly to the U.S. Treasury. On a $60,000 salary, those two halves equal $7,440 a year. Exactly $0.00 of it went into an account bearing your name. Every single penny went out immediately as a check to a current retiree or a disabled American.
The entire system rests on a beautifully simple, multi-generational promise: Today's workers carry today's retirees, and tomorrow's workers will carry us. For decades, more money came in than went out. But instead of saving the surplus, Washington borrowed the extra cash, spent it on daily government operations, and left a stack of non-marketable IOUs in a drawer. Federal bureaucrats call that paper a "trust fund." In reality, calling it a trust fund is like putting an IOU in your kid's piggy bank and telling them their college tuition is fully funded.
Since 2021, the program has paid out more than it takes in. To cover the shortfall, the government has been cashing those IOUs, forcing the Treasury to borrow massive amounts from the public. By 2034, the drawer for the combined retirement and disability funds will be completely empty. By law, that means every retiree's check will instantly face a devastating 17% automatic haircut.
Enter Brian Poindexter, the Democratic candidate for Congress in Ohio's 7th District. He claims he can fix it. Today, the Social Security tax stops once a worker earns $184,500 in a year. His plan calls for three dramatic shifts: remove that income limit so high earners pay on every dollar, let people collect full checks at a younger age, and make the checks bigger. Removing the cap, he confidently promises, "will instantly make it solve."
It doesn't. Poindexter's math operates on the unique assumption that you can cure a leaky roof by building a second story out of cardboard.
When you strip the rhetoric away, his plan is a massive tax increase. By Social Security's official scores, the new tax revenue comes to about $17 trillion in today's dollars. In the version most favorable to the program, the workers who pay it get absolutely no benefit increase for their extra contributions. Yet, even with all that new revenue, the program would still spend more than it collects every single year.
The tax hike alone would buy the system more time, but the rest of Poindexter's plan recklessly spends the money before the Treasury even receives it. A younger retirement age means more people drawing checks for more years, and larger checks cost significantly more every single month. He is trying to pay off a maxed-out credit card by upgrading to a platinum card with a higher limit.
When you run the expert scores, these new promises swallow almost the entire tax hike. Add even a modest 5% raise in baseline benefits, and Social Security ends up deeper in the hole than if Congress did absolutely nothing at all. It takes a special kind of financial alchemy to raise taxes by $17 trillion and still leave the program more broke than you found it.
Worse, this plan accelerates our looming national debt crisis. History proves that if Washington gets its hands on new tax revenue, Congress will spend every dollar of the projected savings elsewhere, just as it spent every Social Security surplus before. When the IOUs inevitably come due, the Treasury will have to borrow heavily from the public at whatever interest rate lenders demand.
The economic climate has shifted drastically. Last year, Washington paid an average of 3.4% on its debt, well above the 2.7% average of the prior two decades. Higher rates on an exponentially larger mountain of debt make the nation's interest bill climb at a terrifying pace. If rates average 5% and Washington keeps spending the way it has for 20 years, net interest will devour half of every single federal tax dollar by 2044.
Using the new tax strictly to borrow less would push that fiscal doomsday back to 2048.
Poindexter’s reckless plan for Social Security will bankrupt the system 6 years sooner. The plan raises taxes, explodes spending, and brings the catastrophic debt crunch closer to today's workers.
Anyone who has fished with a baitcasting reel knows the dreaded backlash. The spool spins faster than the line, the line snarls into a horrific bird's nest, and you are forced to crank the lure home anyway. You might get the lure back, but you cannot cast again until someone meticulously picks out the knot. Poindexter's campaign strategy relies entirely on voters never looking closely at the reel.
Fixing SSI requires smart people who can make tough decisions based on good math. Anything less is a political illusion that works only if you don't ask where the money goes, leaving the next generation holding a hopelessly tangled mess. Poindexter's ideas to fix SSI are dangerous and will destroy the most important safety net for our senior citizens.
Now is not the time to send someone to Congress who doesn’t know a backlash when he sees it. Before you cast your vote, ask every candidate for Congress one simple, non-negotiable question: In what exact year does your plan run out of money? If their answer is "never," demand to see the experts' score.
Editor's Note: Do you enjoy PJ Media's conservative reporting exposing the radical left and woke media? Support our work so we can keep bringing you the truth.
Join PJ Media VIP and use promo code FIGHT to receive 60% off your membership.
Join the Conversation
VIP members get the ability to comment on articles.