
Back at the beginning of this century, the U.S. national debt was $5 trillion. The U.S. budget was $1.78 trillion, and we ran a $237 billion budget surplus.
Today, the debt is $40 trillion; the budget is $7.4 trillion, and the budget surplus is long gone, replaced by a $2 trillion deficit.
Massive amounts of private capital pouring into the AI buildout now compete with government borrowing, which has raised interest rates and threatens to reignite inflation, just as Milton Friedman predicted in the 1980s.
In 2000, France's national debt was around $900 billion, or 58% of its gross domestic product (GDP). Its budget deficit was less than 2% of its GDP.
Today, France is caught in a debt trap that could lead the nation into default and blow up the entire European Union.
"Borrow too much — and public debt is already at €3.6 trillion, accounting for 119% of GDP — and creditors will get so nervous that they start selling," writes UnHerd's Wolfgang Muchau. "With more sellers than buyers, interest rates go up." This raises future debt servicing costs, as it has in the U.S., where we are now spending more than $1 trillion every year to pay creditors on the bonds and other financial instruments we owe. Debt-servicing costs have roughly doubled compared to post-pandemic baselines.
France, a smaller economy, will be unable to absorb the increase in debt servicing. The U.S. can handle it because our economy is $37 trillion, compared to France's $3.6 trillion. There are no palatable choices to escape this debt trap.
UnHerd:
When nations fall into a debt trap, there are four potential escape routes. Perhaps the starkest option is simply defaulting on their debt. Then there are two forms of belt-tightening: either enforcing austerity via higher taxes and lower spending, or selling state-owned land or companies. Finally, central banks can bankroll their governments and print more money, which in practice means buying government debt. That last strategy helps push interest rates down, much like what has been happening lately in Japan.
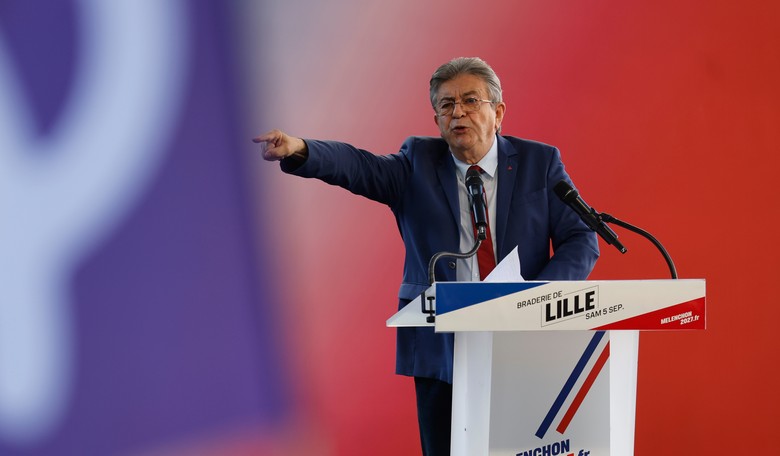
Politics determines which combination of those four options are chosen. The French electorate has for quite some time not voted for candidates who prioritise balancing the budget, something considered distinctly uncool within the country’s political culture. Indeed, the two candidates which polls now predict most likely to enter the second round of the next presidential elections also happen to be the least fiscally responsible: Marine Le Pen, leader of the Right-wing National Rally, and Jean-Luc Mélenchon, head of La France Insoumise, which translates as “France Unbowed."
"The fact that young people are setting wheelie bins on fire is in some ways a distraction from the root causes of all this political instability," writes Munchau. "For, despite the echoes of 1789, 1830, 1848, 1871, and 1968, when youthful revolutionaries challenged Europe’s established order, the generational politics of 2026 is very different."
Indeed, young people in France, Germany, Belgium, and Italy have taken to the streets, and they don't really know why. Is it really over dilapidated schools, as in France, or because of budget cuts, as in Italy and Germany?
"A clue for the European young: It’s not Donald Trump or Benjamin Netanyahu or whoever else you want to burn in effigy," writes Niall Ferguson in The Free Press. "Mais, non: It’s your grandparents."
Youth just matters less than it used to. The age group that historically is most inclined to riot is 15 to 24. Back in 1968, that was a significant proportion of the French (and South Korean) population: 16 percent and 18 percent respectively. Today, the youth share is much lower—12 percent and below 10 percent—whereas in India it has grown from 16.6 percent to 17.5 percent. That helps explain why India’s “cockroach” movement, a student protest movement, has been so much more politically effective than today’s French school protests.
As is well known, Europe has relatively generous welfare systems, which do more taxing and redistributing than their U.S. equivalents. It’s just that these systems were designed for 2.5 children per family and an average life expectancy of 62, not 1.25 and 79. With a few exceptions, the various European models are in the early phase of a nosedive into insolvency.
For Europe, it's only going to get worse. "Across the OECD, the dependency ratio is forecast to rise from 32.6 seniors per 100 people of working age in 2024 to 55.2 in 2054—a 69 percent increase," Ferguson writes. "The working-age population will decline by 13 percent over the next four decades across the OECD. (In Italy, Latvia, Lithuania, and Poland, the decline will exceed 35 percent.)"
This is the demographic catastrophe facing Europe that it tried desperately to head off by importing 3 million immigrants in the 2010s. Not only didn't the newcomers assimilate, but they also became a crushing burden on EU governments.
"France falls into the category of countries that are too big to fail — and too big to save," observes Munchau. "If it refuses austerity for political reasons, it will also refuse the sale of assets." France is not going to sell off the Louvre or historic castles or other buildings. This means the lender of last resort, the European Central Bank (ECB), will have to step in.
Muchau writes that "the ECB could take its support to such extreme levels that the eurozone itself ends up with higher debt and inflation, with other countries lining up to demand support." That would be the beginning of the EU's end. And if either Marine Le Pen's National Rally or Jean-Luc Mélenchon's La France Insoumise (which translates as “France Unbowed") wins the elections next year, France remaining in the EU will not be a high priority for either candidate.
Call it a "debt trap" or a demographic "doom loop," it all adds up to a crisis where the most radical parties of both the left and the right will rise to the top of the heap.
And the grand experiment in forging one continental government out of a bunch of historically adversarial nation-states may finally end in blood.
Exclusively for our VIPs: Columbus: The Good, the Bad, and the Wrongheaded Reason to Hate Him